close

August 2026

Fashion

Get a Flawless Base With the Right Makeup Sponge

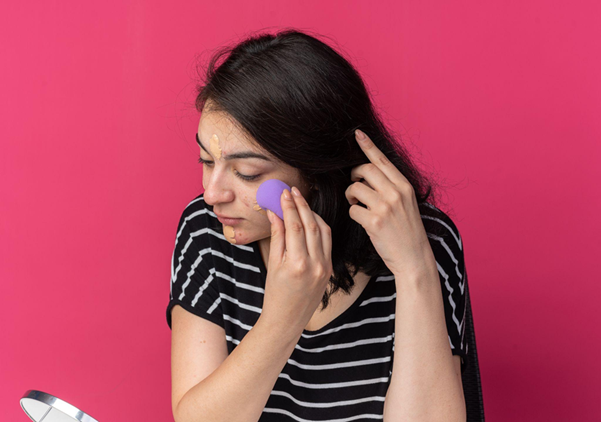
A flawless makeup base does not always depend on using more foundation or owning a huge collection of beauty products. Sometimes, the tool you use makes the biggest difference. A Makeup Sponge can help blend foundation, concealer, cream blush, and other complexion products for a smoother, more even-looking finish. With the right sponge and a simple technique, your makeup can look polished without feeling heavy or overdone.

Why Is a Makeup Sponge So Useful?

Ever applied foundation and noticed streaks around your nose, uneven coverage on your cheeks, or visible lines near the jaw? The issue may not be your foundation at all. It could be the way the product is being blended.

A sponge helps distribute makeup gradually across the skin. The soft bouncing motion blends product instead of dragging it from one area to another. This can create a more seamless finish, especially when you want your foundation to look closer to skin rather than sitting on top of it.

Sponge vs Brush Which Works Better?

A brush and a sponge can both be useful, but they create slightly different effects. Brushes are helpful when you want quick application or more concentrated coverage. A sponge is often better when you prefer a softer, diffused finish.

You do not have to choose only one. Many people apply foundation with a brush and then use a sponge to soften visible lines and blend the edges for a more natural result.

How to Choose the Right Makeup Sponge

Choosing the right tool becomes easier when you focus on your routine rather than the number of options available.

Consider the Shape

Rounded sponge shapes are useful for larger areas such as the forehead and cheeks. Pointed ends can reach smaller areas around the nose and under the eyes, while flat sides can help with controlled application.

If you want one versatile tool, choose a shape that gives you access to both broad and detailed areas.

Check the Texture

A good makeup blending sponge should feel soft and flexible. If it feels rough or overly stiff, it may be uncomfortable and make blending harder.

The texture should allow you to bounce the sponge lightly across the skin without unnecessary pulling.

Wet or Dry Which Works Better?

The answer depends on the finish you prefer and the formula you are using.

Using a Damp Sponge

A damp sponge is popular for foundation because it can create a fresh, natural finish. Soak the sponge, squeeze out excess water, and make sure it is damp rather than dripping wet.

This technique can also help you blend product more easily and achieve lighter-looking coverage.

Using a Dry Sponge

A dry sponge can provide a more concentrated application and may work well when you want stronger coverage. Try both methods with your usual base product to see which gives you the finish you prefer.

How to Apply Foundation With a Sponge

Start with a small amount of foundation. Place it on the centre of your face and gently bounce the sponge outward.

Do not rub or sweep aggressively. Short, controlled tapping motions help blend the product while keeping coverage even.

If you need more coverage, add another thin layer instead of applying a large amount at once. This can help prevent a heavy or cakey finish.

Use the Pointed End for Detail

The pointed side is particularly useful around the sides of the nose, under the eyes, and near the corners of the mouth. These areas can be difficult to reach with a larger sponge surface.

For concealer, use gentle tapping motions rather than pressing the sponge too hard against the skin.

Can You Use a Sponge for Other Makeup?

A Makeup Sponge is not limited to foundation. Depending on the formulation, it can also be useful for concealer, cream blush, liquid contour, and some highlighters.

For cream blush, tap a small amount onto the cheeks and blend the edges gently. This creates a softer result than placing a large amount of pigment directly onto the skin.

Beauty brands such as Simply Nam also offer easy-to-use makeup products that can work well with simple application techniques. When choosing a sponge, think about the products you already use and the type of finish you enjoy rather than following every new beauty trend.

How to Keep Your Makeup Sponge Clean

A makeup tool that touches your skin regularly should be cleaned properly. Wash the sponge after use with a gentle cleanser or a product designed for makeup tools.

Rinse it thoroughly and leave it somewhere clean and well ventilated to dry. Avoid putting a damp sponge straight into a closed makeup bag.

Replace the sponge when it starts tearing, develops an unusual smell, or becomes difficult to clean. A clean, well-maintained sponge is also easier to use.

Common Mistakes to Avoid

One of the easiest mistakes is pressing the sponge too hard. You only need gentle bouncing motions to blend most products effectively.

Another mistake is using too much foundation and expecting the sponge to fix it. Start with less product and build coverage gradually.

Using the same dirty sponge for weeks without proper cleaning is another habit worth avoiding. Regular washing helps keep your tool in better condition and makes application more comfortable.

What Makes a Sponge Worth Buying?

When comparing options for the best makeup sponge, do not focus only on appearance. Consider softness, flexibility, durability, shape, and how well the sponge works with the products you use most often.

A good sponge should make makeup application feel easier, not more complicated. It should blend without excessive effort and help you control how much product ends up on your skin.

Conclusion

The right Makeup Sponge can make foundation and other complexion products much easier to apply and blend. Choosing a suitable shape, using the right amount of moisture, and working in thin layers can help you achieve smoother and more natural-looking coverage.

Whether you prefer a beauty blender for makeup or another sponge design, the key is learning how it works with your routine. Keep it clean, use gentle bouncing motions, and avoid applying too much product at once. With a little practice, a good sponge can become one of the most useful tools in your everyday makeup kit.
read more
Shopping

How to Buy Girls’ Clothes Online in Singapore: A Practical Guide

How to Buy Girls Clothes Online in Singapore A Practical Guide

Key Takeaways

  • Learn how to navigate girls’ clothes online with confidence from day one
  • Understand how to choose the right girls’ dress options for different occasions
  • Discover practical ways to build a versatile wardrobe using kids’ clothes in Singapore
  • Avoid common mistakes during your first 100 days of online shopping

Introduction

Shopping for children’s clothing has evolved into a largely digital experience, offering convenience, variety, and accessibility. The shift to buying girls’ clothes online comes with uncertainty, especially when balancing quality, sizing, and style preferences. Whether you are looking for newborn clothes in Singapore or outfits for toddlers, breaking the journey into practical stages makes it easier to make informed decisions, particularly when selecting a girl’s dress in Singapore that fits both occasion and comfort.

Comprehending the Landscape of Online Choices

The range of girls’ clothes online can feel overwhelming, with options spanning casual wear, occasion dresses, and seasonal collections. At this stage, the goal is to understand what works for your child’s needs and lifestyle. Parents often begin by browsing curated collections, which focus on classic, structured designs when searching for a girl dress in Singapore for their children.

Unlike in-store shopping, online purchases rely heavily on measurement guides. Taking time to compare size charts with your child’s actual measurements helps reduce returns and ensures a better fit. When considering a girl’s dress in Singapore, it is also useful to think beyond aesthetics. Fabric choice, ease of movement, and maintenance requirements all play a role in determining whether it will be worn frequently or set aside after one use.

Building a Functional and Flexible Wardrobe

You may notice which styles your child prefers, which fabrics hold up best, and how different pieces perform in daily use. This is the stage where intentional wardrobe building begins. A practical approach involves mixing everyday essentials with a few standout pieces, including quality newborn clothes in Singapore for growing families. Shopping for kids’ clothes in Singapore during this phase often becomes more strategic. This reduces unnecessary purchases and helps maintain a balanced wardrobe. Children’s clothing must withstand frequent washing and active use. Observing how garments hold their shape and colour over time provides valuable insight into quality, guiding future purchases of girls’ clothes on online platforms.

Refining Style and Making Smarter Choices

By now, you are likely familiar with preferred brands, reliable sizing, and the types of clothing that suit your child’s routine. This allows for more confident and efficient shopping. At this stage, selecting a girl dress in Singapore becomes less about trial and error and more about purposeful choice. Consider details such as stitching, lining, and versatility. Dresses that can transition between settings offer greater value.

Instead of frequent small purchases, some parents opt for fewer, higher-quality items. This aligns with a more sustainable approach to kids’ clothes in Singapore, reducing waste while ensuring that each piece serves a clear purpose. Additionally, familiarity with shopping for girls’ clothes online allows you to take advantage of seasonal releases or curated collections. This saves time and ensures access to designs that align with your preferences.

The Hidden Value Behind Online Shopping

The true value of buying girls’ clothes online lies in the ability to compare options and make informed decisions. Detailed product descriptions, size guides, and customer feedback all contribute to a more transparent shopping experience. This level of information allows parents to evaluate clothing beyond its appearance. Fabric composition, care instructions, and design features inform decision-making processes, leading to more thoughtful purchases. What initially feels uncertain becomes a structured process, where each purchase contributes to a cohesive and functional wardrobe.

Common Mistakes to Avoid

The variety available in buying girls’ clothes online can lead to impulsive decisions, resulting in unused items. Taking a gradual approach helps prevent overlooking practicality, even when purchasing newborn clothes in Singapore that babies quickly outgrow. Evaluating how a girl’s dress in Singapore fits into your child’s routine ensures better usage. Consistently referring to measurement guides and reviews helps mitigate this risk when shopping for kids’ clothes in Singapore.

Conclusion

By approaching girls’ clothes online with a structured mindset, parents can move from uncertainty to confidence. From understanding sizing and quality to building a versatile wardrobe and refining choices, each stage contributes to a more effective shopping experience. Selecting the right girls’ dress in Singapore and integrating it into a practical wardrobe highlights the balance between style and function. Ultimately, shopping for kids’ clothes in Singapore becomes less about convenience alone and more about thoughtful decision-making. With the right approach, it is possible to create a wardrobe that supports both comfort and everyday life.

Ready to build a thoughtful wardrobe for your child? Contact Château de Sable for curated girls’ clothes designed with everyday comfort in mind today.

read more
Home Improvement

How to Maintain Silver-Painted Walls and Surfaces

How to Maintain Silver Painted Walls and Surfaces

Silver-painted walls and surfaces draw attention because light moves across them differently from ordinary flat colours. That same reflective quality can make dust, fingerprints, scratches and uneven touch-ups easier to notice. 

Maintenance therefore needs a light hand. Regular dusting, careful cleaning and timely surface repair usually work better than harsh scrubbing or repeated repainting.

Start with Gentle Dust Removal

Loose dust should be removed before any damp cleaning begins. Otherwise, fine particles may drag across the paint and leave faint marks.

Use a soft microfibre cloth or a clean duster, working from the top of the wall downwards. Pay attention to corners, ledges, mouldings and areas near switches. Avoid rough brushes, particularly on smooth or metallic finishes, as they may disturb the surface sheen.

Clean Marks without Soaking the Surface

Silver paint should not be treated like a tiled or stone surface. Too much water or pressure may leave a visible patch.

Test a soft, damp cloth on a less noticeable area first. Wipe gently and dry the spot soon afterwards. Strong household cleaners, abrasive pads and repeated circular rubbing are best avoided unless the paint manufacturer specifically permits them. For stubborn marks, follow the care guidance supplied with the coating.

Keep Shade Information For Future Touch-Ups

Touch-ups are most successful when the replacement paint matches both the original colour and its finish. Keep the shade name, product details and leftover paint after the first application.

Before preparing a fresh repair batch, reading about ’How to Make Silver Colour?’ can help explain how changes in white, black, blue and metallic pigment affect the final tone. This is useful when checking why a new silver mixture looks cooler, darker or less reflective than the existing wall.

Repair the Base before Repainting

Fresh paint cannot hide a loose, cracked or uneven surface for long. Deal with the damaged base before touching up the silver coat.

A suitable paint ancillary product may be needed where dents, pinholes or rough patches have developed. Clean the area, remove loose material and allow any moisture problem to be resolved. Sand repaired sections carefully so their edges do not remain visible beneath the final coat.

Use a Relevant Product for Wall Repairs

Nerolac Ready Mix Primer Plus Putty may be considered when a ready-to-use, self-priming wall putty is suitable for preparing an interior wall repair. Its purpose here is to help create a smoother base before the silver finishing coat is reapplied. Always check surface compatibility and follow the stated application guidance.

Match the Original Sheen

A colour match alone may still leave the repair visible. Silver surfaces react strongly to differences between matte, satin and glossy finishes.

Use the same paint type and application tool wherever possible. Stir stored paint thoroughly, apply a small amount and allow it to dry before judging the result. A broad patch may blend better than a small, hard-edged spot. 

Store leftover paint in a sealed container, label it and keep it away from heat, moisture and direct sunlight until another repair is needed.

Reduce Moisture and Repeated Contact

Marks often return when the cause remains. Keep furniture edges away from painted walls, improve ventilation in damp rooms and address leaks before repainting. Frequently touched surfaces may need more regular, gentle wiping.

Final Thoughts

Silver-painted walls stay neater when maintenance is simple and consistent. Remove dust carefully, clean marks without force and repair the base before applying fresh colour. Keeping the original shade and finish details also makes later touch-ups easier to manage.

read more
Finance

When Does the Stock Market Become a Plan Instead of a Bet?

When Does the Stock Market Become a Plan Instead of a Bet

The Stock Market gives investors access to ownership in listed companies, but participating in it successfully requires more than reacting to price movements. A structured approach begins with financial goals, investment horizon, risk tolerance, diversification, and a clear process for evaluating securities. Without these elements, market participation can easily become driven by excitement, fear, or short-term speculation.

The market can serve very different purposes for different people. Some investors may be building long-term wealth, while others may be saving for future financial goals. The right approach depends on how much risk can be accepted and how long the capital can remain invested.

The Market Is a Place for Ownership, Not Just Trading

Buying a listed share means acquiring ownership in a business.

This means the investor is exposed to factors such as:

  • Revenue growth
  • Profitability
  • Debt
  • Management quality
  • Industry trends
  • Competitive position

Short-term prices can fluctuate for many reasons, but over longer periods, business performance becomes an important part of the investment outcome.

Treating the stock market only as a place to guess price direction can lead to inconsistent decisions.

Financial Goals Should Determine Market Exposure

Before investing, define what the money is intended to achieve.

Possible goals may include:

  • Retirement
  • Long-term wealth creation
  • Education funding
  • Building capital for a future purchase

The time available before the money is needed affects how much market volatility can be tolerated.

Money required within a few months should generally be treated differently from money that can remain invested for many years.

Risk Tolerance Is More Than Comfort With Losses

Risk tolerance is often described as how much market decline an investor can emotionally accept.

Financial capacity matters as well.

Someone may feel comfortable with volatility but still need the money soon.

A realistic risk assessment considers:

  • Income stability
  • Emergency savings
  • Existing debt
  • Investment horizon
  • Financial responsibilities

The amount invested should reflect both emotional and financial capacity.

Market Capitalisation Helps Differentiate Companies

Listed companies are commonly grouped by market capitalisation.

Broad categories can include:

  • Large-cap
  • Mid-cap
  • Small-cap

These groups can differ in:

  • Business maturity
  • Liquidity
  • Growth potential
  • Volatility

Smaller companies may offer stronger growth potential in some situations, but they can also carry higher business and liquidity risk.

Diversification across company sizes can help reduce concentration.

Sector Allocation Matters as Much as Stock Selection

A portfolio containing many shares can still be concentrated if most belong to the same industry.

For example, holding eight banking stocks does not create the same diversification as holding companies across several unrelated sectors.

Investors can review exposure to areas such as:

  • Financial services
  • Technology
  • Healthcare
  • Consumer businesses
  • Industrials
  • Energy

Sector diversification can reduce dependence on one economic trend.

Index Movements Do Not Tell the Whole Market Story

Headline indices can rise even when many individual stocks fall.

This can happen when a small number of large companies have significant index weight.

Investors should avoid assuming that every stock is performing well simply because a major index is positive.

Looking at:

  • Market breadth
  • Sector performance
  • Volume
  • Individual company results

can provide broader context.

Earnings Seasons Create Useful Research Opportunities

Quarterly and annual results provide information about how companies are performing.

Investors can examine changes in:

  • Revenue
  • Profit
  • Margins
  • Debt
  • Cash flow

Management commentary can also provide context about future demand, expansion plans, and industry challenges.

One strong quarter should not automatically determine an investment decision.

Longer trends are usually more informative.

IPOs Add a Different Type of Market Decision

An initial public offering allows a company to offer shares to public investors.

Unlike evaluating a company with a long listed history, IPO analysis may rely more heavily on:

  • Offer documents
  • Business model
  • Financial history
  • Promoter background
  • Use of proceeds
  • Valuation

An Ipo Investment should therefore be assessed independently rather than based mainly on market excitement, subscription levels, or expectations of listing-day gains.

A heavily discussed IPO can still be expensive or carry significant business risks.

Valuation Helps Separate a Good Company From a Good Investment

A company may have:

  • Strong growth
  • High profitability
  • Experienced management

but still trade at a valuation that assumes very optimistic future performance.

Common valuation measures include:

  • Price-to-earnings ratio
  • Price-to-book ratio
  • Enterprise value metrics

These ratios should be compared with:

  • Historical levels
  • Industry peers
  • Growth rates

Valuation does not predict exactly when prices will rise or fall, but it can help investors avoid paying any price for a good business.

Volatility Should Be Expected Rather Than Feared

Stock markets do not move upward in a straight line.

Corrections and temporary declines are normal features of equity investing.

A portfolio may fall because of:

  • Economic concerns
  • Interest-rate changes
  • Global events
  • Company-specific issues

The appropriate response depends on why the investment was made and whether the underlying thesis has changed.

Reacting to every decline can lead to emotional decisions.

Market Timing Is Difficult to Execute Consistently

Many investors attempt to buy at the exact bottom and sell at the exact top.

This requires correctly predicting both entry and exit points.

Doing that consistently is difficult.

A more structured approach can involve:

  • Investing gradually
  • Maintaining asset allocation
  • Reviewing fundamentals
  • Rebalancing periodically

This reduces dependence on one perfect market call.

Cash Allocation Also Has a Role

Not every rupee needs to remain invested at all times.

Maintaining some liquidity can help investors:

  • Meet short-term needs
  • Avoid forced selling
  • Take advantage of future opportunities

Emergency money should generally remain separate from equity capital.

Selling stocks during a market decline to meet an urgent household expense can turn temporary volatility into a permanent loss.

Corporate Governance Should Not Be Ignored

Strong financial growth does not eliminate governance risk.

Investors should monitor:

  • Related-party transactions
  • Auditor changes
  • Promoter pledging
  • Unusual capital allocation
  • Regulatory issues

Poor governance can undermine otherwise attractive financial performance.

Qualitative analysis therefore matters alongside numerical analysis.

Dividends Are Only One Part of Returns

Some investors prefer companies that distribute dividends.

Dividends can provide periodic cash flow, but they should not be evaluated in isolation.

A high dividend yield may sometimes appear because the share price has fallen sharply.

Investors should also review:

  • Earnings sustainability
  • Payout ratio
  • Business reinvestment needs

Total return can come from both dividends and capital appreciation.

Portfolio Reviews Should Follow a Schedule

Checking prices constantly can encourage unnecessary action.

A more disciplined review may focus on:

  • Earnings updates
  • Major corporate developments
  • Allocation changes
  • Changes in financial goals

The frequency of review should match the strategy.

A long-term investor may not need to react to every intraday movement.

Selling Requires a Defined Reason

Buying rules receive a great deal of attention, but exit decisions are equally important.

A sale may be considered when:

  • The investment thesis changes
  • Business quality deteriorates
  • Valuation becomes difficult to justify
  • Portfolio concentration becomes excessive
  • Financial goals require the money

Selling only because the share price temporarily falls can conflict with a long-term strategy.

Different Assets Can Serve Different Roles

Equity does not need to be the only component of a financial plan.

Depending on an investor’s goals and risk profile, a Mutual Fund may provide another way to access diversified investments without selecting each individual company directly.

The broader objective is to choose investment vehicles according to goals, time horizon, diversification needs, and ability to manage risk.

Conclusion

The Stock Market becomes more useful when participation is connected to a structured financial plan rather than short-term prediction.

Investors can improve discipline by defining goals, understanding risk tolerance, diversifying across companies and sectors, reviewing valuations, analysing business fundamentals, and separating emergency money from market capital.

Market volatility cannot be removed, but a clear process can reduce the likelihood that temporary price movements dictate every decision.

FAQs

1. What is the Stock Market?

The Stock Market is a marketplace where shares of listed companies are bought and sold. Investors can participate in the ownership and potential financial performance of these companies.

2. Is the Stock Market suitable for beginners?

Beginners can participate, but they should first understand basic concepts such as diversification, valuation, business fundamentals, and risk management.

3. Why do stock market prices change every day?

Prices move based on supply and demand, company news, earnings, economic conditions, market sentiment, and global developments.

4. How can investors reduce stock market risk?

Diversification, appropriate position sizing, long-term planning, research, and keeping emergency funds outside the market can help manage risk.

5. Should investors track the market every day?

Not necessarily. The right monitoring frequency depends on the strategy. Long-term investors may benefit more from reviewing business performance and portfolio allocation than from watching every daily price movement.

read more
Finance

How Should You Trade Stocks Without Letting Speed Replace Discipline?

How Should You Trade Stocks Without Letting Speed Replace Discipline

To Trade Stocks effectively, users need more than quick access to buy and sell buttons. A structured approach should combine research, account readiness, order selection, position sizing, liquidity checks, cost awareness, and clear exit rules.

The market can move quickly, but speed alone does not improve decision quality. Traders and investors should know why a stock is being selected, how much capital is being allocated, what risks are acceptable, and what conditions would lead to an exit. A repeatable process can reduce the influence of emotion and short-term market noise.

Start With a Clear Reason for the Trade

Before placing an order, define why the stock is being considered.

Possible reasons may include:

  • Fundamental strength
  • Earnings improvement
  • Technical setup
  • Sector momentum
  • Valuation opportunity

The reason should be specific enough to evaluate later.

Buying simply because a stock is rising can make it difficult to decide what to do when the price reverses.

Research Should Match the Holding Period

The type of research needed depends on the intended timeframe.

A long-term investor may focus on:

  • Revenue
  • Profitability
  • Debt
  • Cash flow
  • Competitive position
  • Valuation

A short-term trader may give more attention to:

  • Price action
  • Volume
  • Liquidity
  • Support and resistance
  • Market momentum

Using the wrong framework can create confusion.

A short-term trade should not be managed like a multi-year investment unless the strategy was designed that way from the beginning.

Account Readiness Comes Before Execution

Before users can trade eligible securities, the required account setup should be complete and functional.

Users planning to Open Demat Account access should review how the trading, demat, and linked bank arrangements work together.

It is also useful to understand:

  • Available funds
  • Applicable charges
  • Settlement process
  • Account statements
  • Security controls

A smooth setup reduces operational problems after trading begins.

Order Type Can Affect the Final Price

Two common order types are market and limit orders.

A market order generally prioritises execution at available prices.

A limit order allows the user to specify a preferred price.

During fast-moving conditions, a market order may execute away from the last visible quote.

A limit order gives more price control but may not execute if the market never reaches the selected price.

The order type should match the objective of the trade.

Liquidity Matters Before Entry

Liquidity affects how easily a stock can be bought or sold.

Highly liquid stocks may generally have:

  • More active buyers and sellers
  • Tighter bid-ask spreads
  • Easier execution

Low-liquidity stocks may have:

  • Wider spreads
  • Sharper price movement
  • More difficult exits

A stock can look attractive on a chart but still be difficult to trade efficiently if market participation is limited.

Position Size Should Be Decided Before the Order

A common mistake is deciding quantity only according to available capital.

A better approach is to consider how much loss can be tolerated if the trade moves against the original view.

Position size may depend on:

  • Account size
  • Entry price
  • Planned exit
  • Maximum acceptable loss

This makes risk measurable before the trade begins.

Confidence should not determine position size on its own.

Entry and Exit Rules Should Be Connected

A trade should not have a carefully planned entry and an undefined exit.

Before entering, consider:

  • What would confirm the trade?
  • What would invalidate it?
  • Where would profits be reviewed?
  • How much loss is acceptable?

The exit rule can be based on price, time, fundamentals, or another clearly defined condition.

The important point is that it should exist before emotions begin influencing the decision.

Costs Can Change the Real Result

Stock trading may involve applicable costs such as:

  • Brokerage
  • Exchange-related charges
  • Taxes
  • Depository-related charges where relevant

A trade that appears profitable before costs may look different after all charges are included.

This becomes especially important for frequent traders.

Net results provide a more realistic picture than gross gains alone.

Watchlists Can Improve Selectivity

A watchlist can help traders monitor opportunities without acting immediately.

Useful items to track may include:

  • Price
  • Volume
  • Earnings dates
  • News
  • Technical levels

This creates time to wait for the intended setup.

Not every stock that moves quickly needs to become a trade.

Patience is part of execution discipline.

Avoid Turning Losses Into Unplanned Investments

One of the most common strategy errors happens when a short-term trade moves against the trader.

Instead of accepting the planned loss, the position is held and reclassified as a long-term investment.

This changes the strategy after the outcome is already negative.

If a trade was designed as a short-term position, it should generally be managed according to that framework unless new research genuinely changes the thesis.

News Should Be Judged for Relevance

Stock prices react to a constant stream of headlines.

Not every update changes the quality of a trade.

Useful questions include:

  • Does the news affect earnings?
  • Does it change risk?
  • Does it alter the original thesis?
  • Is the movement driven mainly by sentiment?

Filtering information can reduce unnecessary reactions.

Broader Market Conditions Still Matter

A strong individual setup can fail if the wider market moves sharply in the opposite direction.

Traders should therefore pay attention to:

  • Overall market trend
  • Sector movement
  • Volatility
  • Major events

This does not mean every trade should follow the index.

It simply provides context for the level of market risk surrounding the position.

Trading Frequency Should Not Be a Goal

Placing more trades does not automatically create better results.

Frequent activity can increase:

  • Costs
  • Decision fatigue
  • Emotional reactions
  • Exposure to poor setups

A trader may benefit more from fewer well-defined trades than from constant market activity.

Quality of decision-making matters more than transaction count.

Review the Trade After It Ends

Post-trade review can help identify whether the process was followed correctly.

Questions may include:

  • Was the original setup valid?
  • Was position size appropriate?
  • Was the exit rule followed?
  • Did emotion affect the decision?
  • Were costs higher than expected?

A profitable trade can still be poorly executed.

A losing trade can still be well managed if the process was sound.

Platforms Should Make Execution Easier to Understand

Trading Apps can provide access to charts, watchlists, order entry, positions, and transaction history.

The strongest platforms help users clearly see:

  • What order is being placed
  • Current position size
  • Applicable funds
  • Order status
  • Profit or loss

Convenience should support the trading plan rather than encourage unnecessary activity.

Conclusion

To Trade Stocks with greater control, users should combine research, account readiness, liquidity checks, position sizing, appropriate order types, cost awareness, and clear entry and exit rules.

A strong process reduces the need to react emotionally to every market movement. Trading decisions should be based on a defined framework rather than speed, excitement, or recent price action alone.

The most useful approach is one where the reason for entering, the acceptable risk, and the conditions for exiting are understood before the trade begins.

FAQs

1. What does it mean to Trade Stocks?

It means buying and selling eligible shares through recognised market infrastructure using an authorised trading platform or broker.

2. Why is liquidity important when trading stocks?

Liquidity can affect bid-ask spreads, execution quality, and how easily a position can be entered or exited.

3. Should position size be based only on available capital?

No. Position size should also reflect the maximum acceptable loss and the risk of the specific trade.

4. What is the difference between a market order and a limit order?

A market order prioritises execution at available prices, while a limit order allows the user to specify a preferred execution price.

5. Why should traders review completed trades?

Post-trade review can help identify whether the original plan was followed and where the decision process can be improved.

read more
Finance

What Makes a Mutual Fund Suitable for a Specific Financial Goal?

What Makes a Mutual Fund Suitable for a Specific Financial Goal

A Mutual Fund can help investors access a diversified portfolio through a professionally managed investment structure. But selecting a fund should begin with the financial goal, not with whichever scheme has delivered the highest recent return.

Different funds can carry very different levels of market risk, sector exposure, credit risk, interest-rate sensitivity, and volatility. The right choice depends on when the money will be needed, how much fluctuation the investor can tolerate, and what role the fund is expected to play in the broader portfolio.

Start With the Goal Before Looking at Fund Rankings

A fund chosen for retirement twenty years away may look very different from one intended for a goal three years away.

Possible goals include:

  • Retirement
  • Education
  • Home purchase
  • Wealth creation
  • Future family expenses

The investment horizon matters because it affects how much short-term volatility can realistically be tolerated.

The fund should fit the goal rather than forcing the goal to fit the fund.

Fund Category Shapes the Risk Profile

Mutual funds are available across different categories.

These may include:

  • Equity-oriented funds
  • Debt-oriented funds
  • Hybrid funds
  • Other category-specific strategies

Each category can behave differently.

For example, an equity fund may experience larger short-term price fluctuations, while certain debt funds may carry interest-rate or credit-related risks.

The category should therefore be understood before comparing individual schemes.

Recent Returns Can Be Misleading

A fund that performed strongly over the last year may attract attention.

But recent performance can be influenced by:

  • Market cycle
  • Sector exposure
  • Investment style
  • Concentration

A strong recent number does not guarantee that the same trend will continue.

Performance should be interpreted within the fund’s category and investment strategy.

Portfolio Role Should Be Clear

Every fund in a portfolio should have a purpose.

That role may be:

  • Core long-term equity exposure
  • Stability
  • Diversification
  • Goal-specific allocation

If several funds serve essentially the same purpose, the portfolio may become more complicated without becoming more diversified.

A simple portfolio can often be easier to understand and maintain.

Fund Overlap Can Reduce Real Diversification

Owning several funds does not automatically mean the investor is well diversified.

Different schemes may hold many of the same companies.

This can create hidden concentration.

For example, three diversified equity funds may still share many of the same large holdings.

Investors should therefore look beyond the number of funds and consider the underlying exposure.

Risk Tolerance and Risk Capacity Are Different

Risk tolerance refers to how comfortable someone feels with market fluctuations.

Risk capacity reflects how much financial loss the investor can realistically absorb.

An investor may feel comfortable with volatility but still have low risk capacity if the money will be required soon.

Factors that affect risk capacity include:

  • Time horizon
  • Emergency savings
  • Existing debt
  • Income stability
  • Dependents

Both should influence fund selection.

Investing Should Follow an Allocation Plan

A Mutual Fund decision should fit within the broader Investing strategy rather than being selected independently.

For example, an investor may already have substantial equity exposure through stocks or other funds.

Adding another aggressive equity scheme could increase concentration rather than improve diversification.

Before adding a fund, review the total allocation across asset classes and categories.

Expense Ratio Matters Over Time

Mutual funds charge ongoing expenses for managing the scheme.

The expense ratio can affect long-term outcomes, particularly over extended investment periods.

Costs should be considered alongside:

  • Strategy
  • Risk
  • Performance
  • Portfolio fit

The lowest-cost fund is not automatically the most suitable option, but costs should not be ignored.

Exit Load Can Affect Short-Term Redemptions

Some funds may apply an exit load if units are redeemed within a specified period.

Investors should review the scheme terms before investing.

This is especially important if there is a chance the money may be needed earlier than planned.

The investment horizon should match the liquidity requirement.

Direct and Regular Plans Can Differ

Depending on the available structure, investors may encounter different plan types.

These can differ in how distribution-related costs are reflected.

Users should understand the plan being selected and the associated cost structure.

The decision should be based on the level of support required and how the investor intends to manage the portfolio.

Fund Manager and Strategy Need Context

The fund manager plays an important role in actively managed schemes.

However, investors should look beyond the name alone.

Useful factors can include:

  • Investment philosophy
  • Portfolio construction
  • Consistency
  • Risk management

The strategy should remain understandable and aligned with the fund’s stated objective.

Sector Concentration Can Increase Volatility

Some funds may have significant exposure to a specific sector or theme.

This can lead to stronger performance when the sector is doing well, but also sharper declines when conditions weaken.

Investors should check whether the portfolio already has similar exposure elsewhere.

Concentration can be intentional, but it should be understood.

SIPs Can Support Regular Contributions

A systematic investment approach can help investors contribute consistently over time.

This can reduce the need to decide the perfect market entry point every month.

Regular contributions may support discipline, but they do not eliminate market risk.

The value of the investment can still decline during weak market periods.

Lump-Sum Investing Has a Different Timing Profile

A lump-sum investment places a larger amount into the market at one time.

This can create more immediate market exposure.

The choice between lump sum and regular contributions depends on:

  • Available capital
  • Time horizon
  • Risk tolerance
  • Portfolio plan

Neither method is automatically better in every situation.

Review the Fund Without Reacting to Every Market Move

A mutual fund portfolio should be monitored, but not necessarily changed frequently.

Useful review questions include:

  • Is the fund still serving its intended role?
  • Has the strategy changed materially?
  • Is the portfolio too concentrated?
  • Has the investor’s goal changed?

A weak quarter alone may not justify switching.

Frequent changes can disrupt a long-term plan.

Rebalancing Can Restore the Intended Allocation

Market movements can cause the portfolio allocation to drift.

For example, strong equity performance may increase the share of higher-risk assets beyond the original plan.

Rebalancing can help restore the intended allocation.

The purpose is to manage risk, not predict which asset class will perform best next.

Keep Emergency Money Separate

Money required for near-term emergencies should generally remain separate from long-term market-oriented funds.

This reduces the risk of having to redeem investments during an unfavourable period.

Emergency reserves and long-term investments serve different purposes.

They should be managed accordingly.

SIP Can Support Long-Term Consistency

A SIP can help investors automate regular contributions toward a financial goal.

The amount should still be reviewed periodically as income, expenses, and goals change. Increasing contributions over time may help keep the plan aligned with the target, while continuing a contribution that no longer fits the budget can create unnecessary pressure.

Conclusion

A Mutual Fund is most suitable when its category, risk profile, costs, strategy, and portfolio role align with a specific financial goal.

Investors should focus on time horizon, diversification, fund overlap, expense ratio, liquidity needs, and overall asset allocation rather than relying on recent performance rankings. Periodic reviews can help ensure that the fund continues to serve the purpose for which it was originally selected.

The strongest mutual fund portfolio is one where every holding has a clear role and remains connected to the investor’s long-term financial plan.

FAQs

1. How should I choose a Mutual Fund?

Start with the financial goal, investment horizon, risk capacity, fund category, costs, and the role the fund will play in the portfolio.

2. Are recent returns enough to compare funds?

No. Recent performance should be considered alongside category, strategy, risk, consistency, and portfolio composition.

3. Why does fund overlap matter?

High overlap can mean several funds hold many of the same securities, reducing the diversification benefit.

4. How often should a mutual fund portfolio be reviewed?

Periodic reviews are generally more useful than reacting to daily market movement. Review when goals, risk profile, or the fund’s strategy changes materially.

5. Does a lower expense ratio always mean a better fund?

No. Cost matters, but strategy, risk, consistency, and suitability for the portfolio should also be considered.

read more
Auto

Why Regular Maintenance Is The Backbone Of Your Fleet’s Success

Why Regular Maintenance Is The Backbone Of Your Fleets Success

Key Takeaways

For businesses that depend on commercial vehicles, grasping the concept of vehicle downtime is essential. After all, every hour can lead to a loss of around $260, which can accumulate into hefty revenue deficits.

Regular maintenance plays a pivotal role in averting unexpected repairs and minimizing downtime. This investment not only boosts operational efficiency but also enhances profitability.

Opting for a specialized repair shop means technicians possess the relevant experience and access to the appropriate tools needed for maintaining specialty vehicles.

Adhering to Texas state regulations for commercial vehicles is vital. Non-compliance can lead to fines and serious safety issues, underscoring the importance of ongoing staff training regarding regulatory updates.

Regular safety inspections are paramount for maintaining vehicle integrity and compliance. These inspections dramatically lower accident risks while building client confidence in shipments.

Proactive maintenance practices, such as routine oil changes and brake inspections, work to save money by stopping minor issues from turning into expensive repairs.

Routine check-ups enhance fleet performance, ensuring that vehicles operate at peak capacity and efficiently meet customer delivery expectations.

The Critical Role of Timely Commercial Vehicle Repairs

Understanding Downtime: What It Costs Your Business

In the realm of commercial vehicles, recognizing the hidden costs tied to vehicle downtime is absolutely critical. Each minute a vehicle is sidelined translates to not only lost productivity but also a direct blow to the financial bottom line. Imagine this: a delivery truck that’s out of commission fails to meet customer needs, letting competitors seize the moment. This isn’t merely a hypothetical scenario; it’s a daily reality that numerous companies confront.

When downtime strikes, its repercussions can spiral out of control. Lost sales, damaged customer relationships, and the looming threat of penalties in contractual agreements can emerge quickly. Research reveals that the average cost of downtime hovers around $260 per hour, which can equate to thousands during repair durations. Hence, addressing your commercial vehicle repair in Texas swiftly and efficiently becomes more than important.

Businesses often discover that regular maintenance schedules significantly cut down the chances of unexpected repairs. Savvy companies understand that investing in preventative care greatly outweighs the expenses associated with reactive repairs. Routine diagnostics can unveil potential issues before they escalate into major headaches.

The Connection Between Maintenance and Profitability

The relationship between vehicle maintenance and profitability isn’t just talk; it’s a crucial factor steering logistics and transport firms today. Consider this: vehicles that receive timely attention are far less likely to suffer major failures. The cost-benefit analysis is crystal clear. Spend a bit on servicing now, or prepare for large repair bills later. Clearly, the choice speaks for itself.

Regular inspections not only elevate vehicle performance but also strongly influence the operational efficiency of delivering goods and services. Happy clients often lead to more business. As companies adopt maintenance programs, they tend to notice reductions in downtime and noteworthy savings on operating costs. This strategic approach builds a robust foundation for profitability.

“Investing in vehicle maintenance isn’t just about fixing problems; it’s about securing your future.” – Industry Expert

For commercial entities, fostering a proactive maintenance culture can turn potential setbacks into golden opportunities. Those that recognize vehicle upkeep as a cornerstone of their strategy typically stand out amidst fierce competition.

Choosing the Right Repair Service for Specialty Vehicles

What Makes a Repair Shop Specialized?

Selecting the right repair shop for specialty vehicles warrants careful scrutiny. Not every repair shop is equal; specialization can significantly influence outcomes. A specialized shop doesn’t merely fix vehicles; it comprehends the intricacies of specific types – be it coaches, cargo vans, or heavy-duty machinery. The expertise of the technicians in such shops is invaluable.

Here are some distinguishing features of a specialized repair shop:

  • Relevant Experience: Technicians should possess experience working with similar vehicle types.
  • Certification and Training: It’s beneficial to find shops with certified technicians familiar with industry standards.
  • Advanced Tools: Specialty vehicles often demand specific diagnostic equipment that general shops may lack.
  • Thorough Service Offerings: A genuinely specialized shop should understand everything from bodywork to engine calibration.

Investing time to locate a repair facility that specializes can minimize future headaches. A capable shop not only resolves issues but anticipates problems, ensuring vehicles remain in optimal condition over time.

Questions to Ask Before Committing to a Service

Before entrusting a repair shop with a business’s future, there are essential questions to address. Making an informed choice often leads to better outcomes and fewer unexpected challenges.

Consider posing these questions:

  • What experience do you have with my specific type of vehicle?
  • Can you provide references from businesses similar to mine?
  • What’s the estimated turnaround time for various repairs?
  • What warranties do you offer for parts and labor?

These inquiries offer clarity regarding what a prospective repair shop can bring to the table. A shop that embraces these questions signals confidence and openness. Ultimately, the relationship established here can either advance a business or create needless complications.

Maintaining Compliance and Safety Standards in Texas

State Regulations Impacting Commercial Vehicle Operations

Operating a commercial vehicle in Texas often involves navigating a tangled web of regulations. These laws aren’t just administrative barriers; they are crucial for safety on the roads. Regulations span everything from weight limits to emissions standards, and compliance remains vital.

Neglecting adherence to these regulations can lead to steep fines. Texas enforces strict penalties for infractions, which might include vehicle impoundment and escalating civil penalties. Understanding these laws not only keeps businesses in good standing but also enhances their reputation. Ensuring safety compliance is non-negotiable, and collaborating with specialists who grasp these intricacies can boost operational efficiency.

Companies should contemplate scheduling regular training sessions to keep staff updated on evolving regulations. This proactive strategy cultivates a culture of responsibility and safety, shielding businesses from potentially devastating penalties.

Safety Inspections: Why They Shouldn’t Be Overlooked

The importance of conducting regular safety inspections is immense. They represent more than a mere formality; they are critical for ensuring vehicles remain safe on the road. A truck that successfully passes a safety inspection isn’t just compliant; it reflects a commitment to quality service and employee safety.

Consistent safety checks reveal potential issues that could threaten vehicle integrity. Addressing such concerns demonstrates responsible management. Consider the benefits of safety inspections:

  • Mitigate accident risks, contributing to safer roads.
  • Ensure continual compliance with state regulations.
  • Boost client confidence in their shipments.

By prioritizing inspections, businesses cultivate a safety-oriented mindset that resonates throughout their operations. Vehicles become reliable assets that positively impact overall business health.

Maximizing Vehicle Lifespan Through Proactive Maintenance

Key Maintenance Practices That Save You Money

Maximizing the lifespan of commercial vehicles isn’t merely advantageous — it’s essential for financial sustainability. Proactive maintenance practices thwart the escalation of minor issues into major failures. This approach not only saves money but also significantly prolongs a vehicle’s operational life.

Top maintenance practices encompass:

  • Regular Oil Changes: Keeping oil clean is crucial for engine longevity and performance.
  • Tire Rotations and Alignments: These practices ensure safety and optimize fuel efficiency.
  • Brake Inspections: Essential for safety; worn brakes can result in catastrophic failures.
  • Fluid Checks: Monitoring all vehicle fluids regularly can prevent leaks and costly repairs.

The financial reasoning is straightforward. When companies prioritize vehicle maintenance, they spend less on emergency repairs, allowing more focus on growth initiatives. Maintenance is all about foresight and resilience in business.

How Regular Check-Ups Benefit Your Fleet’s Performance

Routine check-ups extend beyond just preventing repairs. They fundamentally enhance fleet performance and reliability. When vehicles receive steady upkeep, overall efficiency rises. A vehicle functioning at maximum capacity reduces costs, accelerates delivery times, and heightens service levels.

So, what’s the bottom line? Investing in regular check-ups directly translates to a well-maintained, efficient operation. Clients want timely deliveries, and dependable vehicles make that possible.

“A vehicle on the road is a revenue-producer; keep it rolling through regular care.” – Fleet Management Specialist

The distinguishing factor between mere functionality and true excellence in this sector often hinges on attention to detail. It’s not just about having vehicles available; it’s about ensuring those vehicles perform at peak levels.

FAQ

What are the long-term benefits of specialized repair services?

Selecting specialized repair services offers businesses tailored expertise that elevates vehicle performance and extends longevity. Over time, this results in lower maintenance costs and fewer breakdowns, leading to enhanced operational efficiency and customer satisfaction.

How can a business ensure compliance with Texas vehicle regulations?

Businesses can maintain compliance by staying informed about state regulations and regularly training staff on updates. Partnering with specialized repair shops skilled in the regulatory landscape simplifies adherence to laws, thus minimizing risks.

What are the signs that a vehicle needs immediate maintenance?

Typical indicators include unusual noises, warning lights illuminating on the dashboard, a decline in fuel efficiency, or changes in handling. Addressing these symptoms promptly can prevent costly repairs and limit downtime.

How often should maintenance checks be scheduled for commercial vehicles?

Most experts recommend scheduling maintenance checks at least quarterly to ensure vehicles remain in optimal condition. However, frequency may vary based on vehicle usage, age, and specific operational needs.

What technology is used in specialty vehicle repairs?

Advanced diagnostic tools and specialized equipment are crucial for the repair of specialty vehicles. This could encompass software for electronic systems, alignment machinery, and hydraulic lifts, all tailored to handle particular vehicle types.

How does regular maintenance contribute to employee safety?

Consistent maintenance diminishes the risk of vehicle failures that could cause accidents. Reliable vehicles create a safer environment for employees, which in turn elevates morale and productivity within the workplace.

What role does driver training play in vehicle maintenance?

Driver training is critical as it promotes awareness of both vehicle handling and safety protocols. Educated drivers are more likely to identify and report issues, leading to timely maintenance and an overall healthier fleet.

Can regular maintenance influence insurance premiums?

Indeed, well-maintained fleets can positively impact insurance premiums. Insurers typically offer better rates for vehicles that are consistently cared for, recognizing the diminished risk of accidents and claims linked with proactive maintenance.

Useful Resources

read more
Finance

A Loan Should Fit Your Repayment Plan Before Your Spending Plan

A Loan Should Fit Your Repayment Plan Before Your Spending Plan

A loan can help meet a financial requirement when available savings are not enough or when using all existing cash would create liquidity problems. People may borrow for education, healthcare, home-related expenses, business needs, vehicles, emergencies, or other planned purposes.

The important decision is not simply whether credit is available. Borrowers need to understand the total cost, repayment schedule, interest method, fees, tenure, eligibility criteria, and the consequences of delayed payments. A manageable borrowing decision starts with the amount that can be repaid comfortably, not the maximum amount a lender is willing to offer.

Define the Purpose Before Applying

Borrowing should begin with a clear reason.

Before submitting an application, identify:

  • Exact amount required
  • Reason for borrowing
  • Expected repayment source
  • How quickly the money is needed
  • Whether another financial option is available

A clear purpose helps prevent unnecessary borrowing.

For example, taking ₹5 lakh when the actual requirement is ₹3 lakh increases interest cost without solving an additional need.

Separate Need From Convenience

Easy digital access can make borrowing feel routine.

A user may see a pre-approved offer or instant eligibility message and assume it should be used.

However, availability does not equal affordability.

A loan should be considered because there is a genuine requirement and a reasonable repayment plan, not simply because approval appears easy.

Check Eligibility Factors Early

Lenders may assess several factors before approving credit.

These can include:

  • Income
  • Employment or business stability
  • Existing debt
  • Credit history
  • Repayment record
  • Age
  • Loan amount
  • Tenure
  • Internal lender policies

Different lenders may use different criteria.

Meeting one eligibility condition does not guarantee approval.

Credit History Can Affect the Offer

A borrower’s credit profile may influence:

  • Approval probability
  • Interest rate
  • Loan amount
  • Tenure
  • Additional verification requirements

A history of timely repayments can support stronger creditworthiness, while repeated missed payments can reduce future borrowing options.

Borrowers should review their credit report periodically and correct genuine errors through the appropriate process.

Compare Interest Rates on the Same Basis

A low advertised rate may not always represent the actual rate offered to every borrower.

The final rate can depend on:

  • Credit profile
  • Income
  • Loan type
  • Tenure
  • Employer or business profile
  • Lender policy

Users should compare the rate applicable to their own application.

They should also check whether the quoted rate is fixed or floating, where relevant.

Understand the Total Cost of Borrowing

Interest is only one part of loan cost.

Possible charges may include:

  • Processing fee
  • Documentation fee
  • Administrative charges
  • Insurance cost where applicable
  • Late-payment penalty
  • Bounce charges
  • Foreclosure charges
  • Prepayment charges
  • Taxes

The total repayment amount provides more useful information than the headline rate alone.

EMI Should Be Tested Against Monthly Cash Flow

An EMI may look affordable in isolation.

The better question is whether it remains affordable after accounting for essential monthly expenses.

Borrowers should consider:

  • Rent or housing cost
  • Groceries
  • Utilities
  • Existing EMIs
  • Insurance
  • School expenses
  • Transport
  • Savings commitments

A loan that leaves almost no monthly buffer can become difficult to manage when an unexpected expense appears.

Use a Conservative Repayment Estimate

Borrowers should avoid assuming that income will always increase.

A more realistic approach is to assess the EMI against current reliable income.

If the loan is manageable only under the assumption of a future salary increase, bonus, or business improvement, the repayment plan may be too aggressive.

Tenure Changes Both EMI and Total Interest

A longer tenure can reduce the monthly EMI.

However, it may increase the total amount of interest paid over the life of the loan.

A shorter tenure usually increases the EMI but may reduce total interest cost.

The right balance depends on:

  • Monthly affordability
  • Income stability
  • Loan amount
  • Interest rate
  • Other financial goals

Borrowers should compare more than one tenure before deciding.

Digital Borrowing Needs Careful App Verification

A loan app can make application, document submission, repayment tracking, and account access more convenient. However, users should verify the actual lender behind the platform before sharing personal or financial information.

Important checks include:

  • Legal lender name
  • Official website
  • Customer support
  • Loan agreement
  • Fee schedule
  • Grievance process
  • Repayment terms

An attractive interface does not replace lender verification.

Read the Loan Agreement Before Accepting

The agreement should explain the borrower’s actual obligations.

Important sections may include:

  • Loan amount
  • Interest rate
  • Tenure
  • EMI
  • Payment dates
  • Charges
  • Late-payment consequences
  • Prepayment terms
  • Default conditions

Users should not accept the agreement without understanding these points.

If a term is unclear, it should be clarified before disbursement.

Avoid Borrowing From Unknown Messages

Unsolicited messages may promise:

  • Guaranteed approval
  • No documentation
  • Immediate disbursement
  • Very low rates
  • No credit checks

These claims should be treated cautiously.

Users should avoid sharing:

  • PAN
  • Aadhaar details
  • Bank credentials
  • OTPs
  • Card information

Sensitive information should only be submitted through verified channels.

Never Pay an Unknown Person for Approval

Some scams ask for an upfront transfer to release the loan.

The payment may be described as:

  • Security fee
  • Approval fee
  • Refundable deposit
  • Verification charge

Users should verify any such request directly with the official lender.

Payments should not be sent to personal accounts or unknown UPI IDs based only on a message or phone call.

Loan Disbursement Should Match the Agreement

Before using the funds, check whether the amount received matches the approved terms.

Sometimes the net amount credited may be lower because certain charges are deducted.

Borrowers should understand:

  • Gross loan amount
  • Deductions
  • Net disbursement
  • EMI basis

This prevents confusion when repayments begin.

Set Up Repayment Before Spending the Money

A strong borrowing habit is to plan repayment before using the loan.

Borrowers can:

  • Keep EMI dates in a calendar
  • Maintain sufficient balance
  • Set reminders
  • Review auto-debit instructions
  • Keep an emergency buffer

This reduces the chance of missing the first few payments because attention is focused only on the borrowed funds.

Do Not Ignore Small Delays

A missed EMI can have consequences beyond a late fee.

Repeated delays may affect:

  • Credit history
  • Future loan eligibility
  • Total repayment cost
  • Collection activity

If repayment difficulty is expected, contacting the lender early is generally more practical than avoiding communication.

Avoid Taking One Loan to Pay Another Without a Plan

Using new debt to cover existing debt can create a cycle.

Before refinancing or borrowing again, the user should understand:

  • Whether the total interest cost reduces
  • Whether the tenure becomes longer
  • Whether fees apply
  • Whether monthly cash flow genuinely improves

A lower EMI does not always mean a cheaper loan.

Prepayment Can Be Useful but Needs Review

Some borrowers may be able to repay part or all of the loan early.

Before doing so, check:

  • Prepayment eligibility
  • Foreclosure charges
  • Minimum holding period
  • Revised interest calculation
  • Closure process

Early repayment can reduce interest cost in some situations, but the benefit depends on the exact product terms.

Keep Loan Documents Until Closure

Important records include:

  • Sanction letter
  • Loan agreement
  • Repayment schedule
  • Payment receipts
  • Statements
  • Closure certificate

These documents should be stored securely.

After full repayment, borrowers should obtain confirmation that the account has been closed.

Review Credit Reports After Closure

After the loan is repaid, borrowers may want to check whether the closure is reflected correctly in their credit report after a reasonable reporting period.

If the account remains incorrectly listed as active or overdue, the issue should be raised through the appropriate lender and credit bureau process.

Borrowing Should Not Replace Emergency Savings

A loan can help during an emergency, but repeated reliance on credit for minor unexpected expenses can be expensive.

Building an emergency fund can reduce dependence on borrowing for:

  • Small medical bills
  • Home repairs
  • Temporary income delays
  • Urgent travel

Even a modest reserve can provide more flexibility.

Avoid Using Credit for Short-Lived Wants

Borrowing for an item that loses value quickly can create a mismatch between benefit and repayment.

The purchase may be forgotten long before the EMI ends.

Before borrowing for a discretionary expense, ask:

  • Is the purchase necessary?
  • Can it be delayed?
  • Can part of it be paid from savings?
  • Will the EMI affect other goals?

This simple check can prevent unnecessary debt.

Conclusion

A loan can be useful when it is connected to a genuine financial need and supported by a realistic repayment plan.

Borrowers should compare interest, fees, tenure, EMI, lender credibility, and prepayment conditions before accepting any offer. They should also evaluate whether monthly income can absorb the repayment without disrupting essential expenses or emergency savings.

The strongest borrowing decisions are based on affordability rather than eligibility. Being approved for a certain amount does not mean that borrowing the full amount is financially appropriate.

FAQs

1. What should be checked before taking a loan?

Borrowers should review the interest rate, processing fees, tenure, EMI, repayment dates, prepayment conditions, lender identity, and total repayment amount.

2. Does a longer loan tenure reduce cost?

A longer tenure can reduce the monthly EMI, but it may increase the total interest paid over the full repayment period.

3. Can missed EMIs affect future borrowing?

Yes. Repeated missed or delayed payments may affect credit history and can make future borrowing more difficult or expensive.

4. Is pre-approved credit automatically a good option?

No. A pre-approved offer only indicates availability under certain conditions. The borrower still needs to assess need, cost, and repayment affordability.

5. Why should loan documents be kept after repayment?

Loan agreements, repayment records, and closure documents can help resolve future discrepancies and confirm that the account was fully repaid.

read more
Finance

Loan Apply Roadmap for Borrowers Who Want Clear Terms

Loan Apply Roadmap for Borrowers Who Want Clear Terms

The Loan Apply process may look simple on a digital platform, but every application creates a potential financial commitment. Borrowers need to understand how much they require, what they can afford, which lender is offering the credit, and how the repayment schedule will affect monthly income.

A quick form should not lead to a rushed decision. Interest rates, processing fees, annual borrowing costs, late-payment penalties, data permissions, and closure conditions should all be reviewed before an agreement is accepted.

This roadmap explains the full journey from identifying a borrowing need to completing formal account closure.

Milestone One Define the Borrowing Purpose

The application should begin with a clear financial reason.

Common borrowing purposes may include:

  • Medical expenses
  • Education fees
  • Essential home repairs
  • Business cash-flow needs
  • Emergency travel
  • Relocation costs
  • Debt consolidation

The purpose helps determine the amount, urgency, and repayment period.

Borrowers should calculate the actual expense and subtract available savings, insurance support, or other resources. The remaining amount becomes the approximate funding gap.

Taking more than the required amount may increase the instalment and total interest without providing any meaningful benefit.

Milestone Two Check Whether Borrowing Is Necessary

Credit should not be the first option for every expense.

Before applying, borrowers can review alternatives such as:

  • Emergency savings
  • Employer assistance
  • Family support
  • Insurance coverage
  • Payment extensions
  • Instalment plans
  • Reduction of non-essential spending

These alternatives may not be available in every situation, but they can reduce the amount that needs to be borrowed.

Repeated borrowing for regular household expenses may indicate a broader budgeting problem that should be addressed separately.

Milestone Three Build an Affordability Estimate

A loan should fit within the monthly budget without affecting essential needs.

Borrowers can list:

  • Net monthly income
  • Rent or housing cost
  • Food and utilities
  • Transport expenses
  • Existing instalments
  • Credit card payments
  • Insurance premiums
  • Education expenses
  • Regular savings

The amount remaining after these commitments indicates the possible repayment capacity.

The proposed instalment should leave some room for unexpected costs. Choosing the highest affordable amount can create pressure when income is delayed or expenses increase.

Milestone Four Review the Credit Profile

Lenders may examine repayment history before approving an application.

A credit report can contain:

  • Previous loans
  • Credit card balances
  • Payment records
  • Overdue accounts
  • Recent enquiries
  • Closed credit accounts

Borrowers should review the report for incorrect or unfamiliar entries.

Possible errors may include a closed account shown as active, an incorrect outstanding balance, or a payment wrongly marked late.

Submitting many applications within a short period can create multiple enquiries. Borrowers should compare options first and apply selectively.

Milestone Five Verify the Lending Institution

A digital application may be operated by a marketplace, service provider, or lender.

Applicants should identify the institution that will approve, disburse, and collect the loan.

Verify:

  • Legal lender name
  • Official website
  • Registration details
  • Agreement issuer
  • Customer service channels
  • Grievance process
  • Repayment account information

The lender should be clearly identified before the applicant uploads identity, income, or banking documents.

Platforms that hide the lender’s name, request advance release payments, or promise guaranteed approval should be avoided.

Milestone Six Compare Interest in Annual Terms

Interest may be displayed in daily, monthly, or annual form.

Borrowers should ask:

  • Is the rate annualised?
  • Is it fixed or variable?
  • How is interest calculated?
  • What is the annual percentage rate?
  • Which charges are included?
  • Can the rate change after approval?

A small monthly percentage may represent a high annual cost.

Offers should be compared using the same loan amount and tenure. Otherwise, the instalment and total repayment figures may not provide a fair comparison.

Milestone Seven Calculate the Full Borrowing Cost

The monthly instalment is only one part of the cost.

Borrowers should also review:

  • Processing fee
  • Documentation charge
  • Verification fee
  • Insurance premium
  • Applicable taxes
  • Late-payment penalty
  • Failed debit charge
  • Foreclosure fee
  • Part-payment charge

Some charges may be deducted before disbursal.

Applicants should request a written breakdown showing the sanctioned amount, total deductions, net amount credited, and final repayment liability.

Milestone Eight Study the Digital Application Flow

A Loan App Online may simplify registration, document upload, verification, offer review, agreement acceptance, and repayment tracking.

However, convenience should not replace document review.

Applicants should check whether the platform clearly shows:

  • Loan amount
  • Lender name
  • Interest rate
  • Annual cost
  • Repayment tenure
  • Instalment amount
  • Charges
  • Due dates
  • Penalties

Temporary screens should not be treated as complete records. Important documents should be downloaded before acceptance.

Milestone Nine Prepare Accurate Documents

Document mismatches can delay approval or lead to rejection.

Common requirements may include:

  • Identity proof
  • Address proof
  • Income records
  • Bank statements
  • Salary slips
  • Tax returns
  • Employment details
  • Business records

Names, addresses, income figures, and bank details should remain consistent across documents.

Applicants should avoid editing or altering records. False information can result in rejection and may create legal or financial consequences.

Milestone Ten Read the Key Fact Statement

The key fact statement should summarise the main borrowing terms.

It may include:

  • Approved amount
  • Interest rate
  • Annual percentage rate
  • Processing fee
  • Repayment tenure
  • Instalment amount
  • Penalty terms
  • Total repayment

Borrowers should compare this document with the offer displayed during application.

Any mismatch should be clarified before digital consent is provided.

A saved copy can also help resolve future disputes.

Milestone Eleven Review the Repayment Schedule

The repayment schedule should clearly explain when and how payments are due.

Applicants should confirm:

  • First instalment date
  • Monthly due date
  • Number of instalments
  • Payment method
  • Auto-debit arrangement
  • Grace-period rules
  • Failed-payment charges

The due date should ideally fall after salary or regular business income is received.

Even when automatic repayment is enabled, borrowers should maintain a separate reminder and confirm that every instalment has been recorded.

Milestone Twelve Understand Late-Payment Risk

A delayed payment can increase costs and affect future borrowing.

Possible consequences include:

  • Penal charges
  • Additional interest
  • Failed debit fees
  • Collection communication
  • Credit bureau reporting
  • Reduced eligibility

Borrowers should understand when a payment becomes overdue and how penalties are calculated.

Anyone expecting temporary difficulty should contact the lender before the due date. Ignoring reminders may reduce the chance of arranging a manageable solution.

Milestone Thirteen Examine Privacy Permissions

A digital credit platform may request access to personal and device information.

Applicants should review requests involving:

  • Contacts
  • Messages
  • Photos
  • Call records
  • Device storage
  • Location
  • Bank information

Only permissions necessary for identity verification, fraud prevention, and account management should be accepted.

The privacy policy should explain how data is collected, stored, processed, shared, and deleted.

Unclear or excessive permissions should be treated cautiously.

Milestone Fourteen Protect the Account

Digital borrowing requires strong security practices.

Borrowers should:

  • Use an official application source
  • Create a unique password
  • Enable biometric login
  • Use two-factor authentication
  • Avoid public devices
  • Review login alerts
  • Update the application regularly

One-time passwords, card PINs, banking credentials, and account passwords should never be shared.

Any request to transfer a fee to a personal account should be verified through official support before action is taken.

Milestone Fifteen Build a Repayment Buffer

A repayment reserve can protect the borrower during temporary financial difficulty.

The reserve may cover one or more instalments during:

  • Salary delay
  • Medical emergencies
  • Job transition
  • Business slowdown
  • Urgent household repairs

Borrowers with irregular income may need a larger buffer than salaried applicants.

The reserve should remain separate from routine spending.

Milestone Sixteen Review Early Closure Terms

Some borrowers may want to reduce the outstanding balance after receiving a bonus or additional income.

Applicants should check:

  • Lock-in period
  • Part-payment eligibility
  • Minimum amount
  • Foreclosure charge
  • Frequency limits
  • Closure process

Early repayment may reduce interest, but the saving should be calculated after including applicable fees.

The lender should provide a written settlement amount before the final transfer is made.

Milestone Seventeen Monitor the Account

Borrowers should review the account after disbursal.

Important details include:

  • Amount received
  • Instalments paid
  • Outstanding principal
  • Interest charged
  • Additional fees
  • Next due date
  • Account status

Payment receipts, bank records, agreements, and support communication should be stored securely.

Unexpected charges should be reported promptly through the lender’s official complaint channel.

Milestone Eighteen Complete Formal Closure

After the final repayment, borrowers should obtain:

  • Final account statement
  • No-dues certificate
  • Closure letter
  • Auto-debit cancellation confirmation
  • Updated credit-report status

These records provide proof that no amount remains unpaid.

Borrowers using different finance apps should keep closure documents organised so that active and completed obligations are not confused during future financial planning.

Conclusion

The Loan Apply process should be completed only after the borrower understands the purpose, cost, lender, repayment schedule, and privacy conditions.

A suitable loan should solve a genuine financial need without creating excessive monthly pressure. Borrowers should compare annual costs, take only the required amount, maintain a repayment buffer, and preserve every important document.

Careful preparation before application can reduce avoidable fees, data risks, and repayment problems later.

Frequently Asked Questions

1. Does submitting an application guarantee approval?

No. Final approval may depend on document checks, income assessment, credit history, and lender policy.

2. Why can the credited amount be lower than the sanctioned amount?

Processing fees, taxes, insurance, or other disclosed charges may be deducted before disbursal.

3. Can the repayment date be changed?

This depends on the lender’s rules. Any approved change should be confirmed in writing.

4. Is a longer tenure always better?

No. It may reduce the monthly instalment but increase the total interest paid.

5. What confirms that the loan is closed?

A final statement, no-dues certificate, closure letter, and updated credit record can confirm formal closure.

read more